
Market Briefing: The Yield Line Test - Markets on Edge Ahead of PCE and Jobs
Sep 28, 2026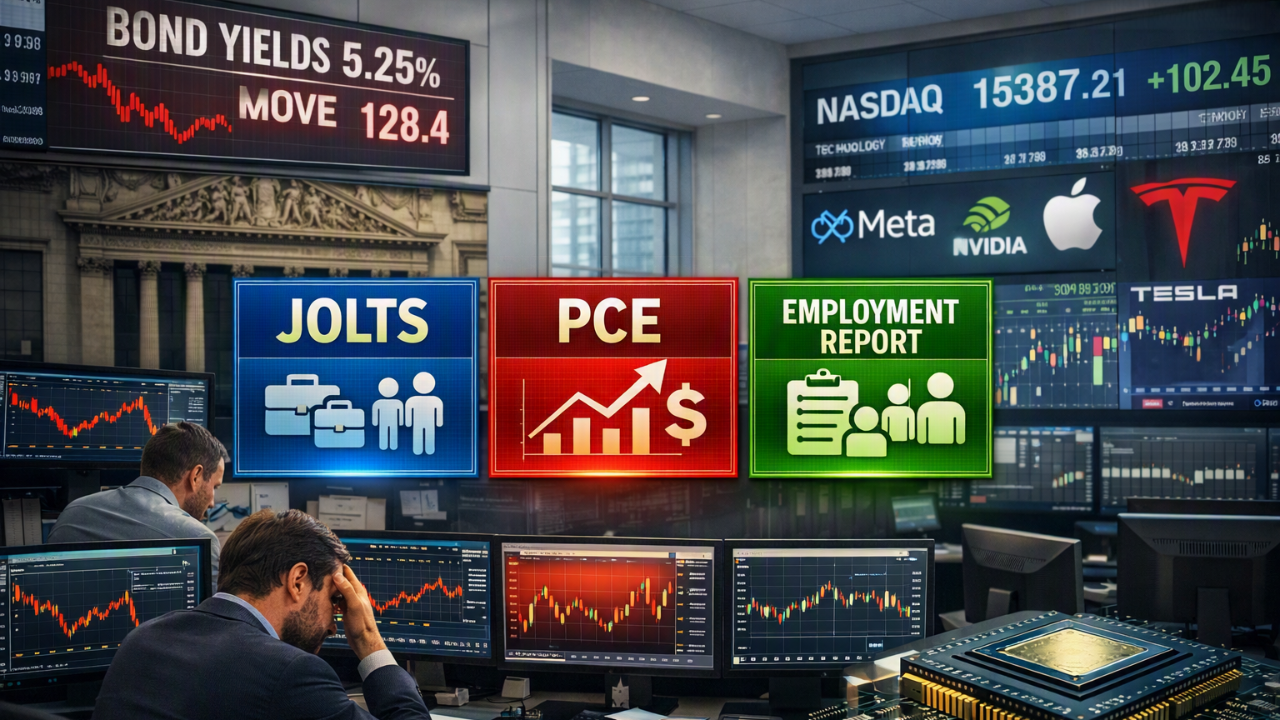
Dear Friends,
The final week of September opens with markets sitting at a crossroads, as surging Treasury yields, spiking bond‑market volatility, and increasingly fragile equity breadth collide with a critical slate of U.S. economic data. Despite the S&P 500 hovering near record highs, the rally rests almost entirely on mega‑cap tech and AI stocks, while financials and rate‑sensitive sectors weaken under the weight of multi‑decade‑high yields. With August PCE and the September jobs report set to land, data the Fed will rely on ahead of its October meeting, this week becomes a decisive test of whether the market’s narrow leadership can withstand mounting bond‑market stress or whether a broader risk‑off shift is about to unfold.
- Macro Setup
- Treasury yields are the dominant force this week. The 10‑year sits near 5.20%, just below a critical breakout level at 5.25%. A move above it opens the door to 5.6%–5.9%.
- Bond‑market volatility (MOVE) has exploded, jumping 27–33% and signaling deep stress in rates.
- Equity volatility (VIX) remains unusually low, creating a dangerous divergence between calm equities and stressed bonds.
- Key Data This Week
- August PCE (Wed):
- Headline expected 0.4% m/m, 3.7% y/y
- Core expected 0.3% m/m, 3.3% y/y Analysts believe PCE is predictable based on CPI/PPI, so less likely to shock markets.
- September Jobs Report (Fri):
- Consensus: ~100k jobs, unemployment 4.1%
- BUT PMI employment surged at its fastest pace since 2022 → upside risk This is the only jobs report before the Fed’s October meeting, making it the most important event of the week.
- Equity Market Structure
- Market breadth is deteriorating sharply.
- NYSE stocks hitting 52‑week lows at the highest level since April 2025
- Only ~51% of S&P 500 stocks above their 200‑day
- Index strength is entirely driven by mega‑cap tech/AI.
- Semis, software, and hyperscalers are carrying the S&P 500 and Nasdaq
- Meta’s AI agent “Muse” sparked a massive rally
- Rate‑sensitive sectors are breaking down:
- Financials, utilities, REITs, homebuilders under heavy pressure
- Major Risks This Week
- Yield Breakout Risk: A hot jobs report could push the 10‑yr above 5.25%, triggering a run toward 5.6–5.9%.
- AI‑Financing Risk: Rising yields increase the cost of funding massive AI‑infrastructure spending. If AI capex slows, the market loses its only strong leadership group.
- Deleveraging Trigger (BofA):
- MOVE > 125
- Global financials ETF (IXG) < 125 → Risk‑off deleveraging event MOVE is already elevated; financials are weakening.
- What the Market Will Focus On
Primary Focus
- Jobs Report (Friday): Decides whether the Fed hikes again in October
- Bond‑market stability: Whether yields break out or stall
- Tech/AI leadership durability: Can it keep carrying the market under rising rates?
Secondary Focus
- Financial sector stress
- Rate‑sensitive sectors (utilities, REITs, homebuilders)
- Corporate bond issuance for AI capex (could push yields even higher)
- Bottom Line
This week is a macro stress test for a market held up almost entirely by mega‑cap tech while the rest of the tape weakens.
- If jobs come in hot → yields break out → MOVE spikes → financials crack → risk‑off.
- If jobs/PCE are tame → yields stabilize → tech continues carrying the market.
- If yields overshoot → policymakers may intervene → bonds/EM/commodities benefit.
Want to get our Stocks to Watch Report every trading day? Get a free 7-day trial of the MyCompass Pro membership!
