
Market Briefing: The Tech Earnings Stress Test vs. a Market in Rotation
Oct 19, 2026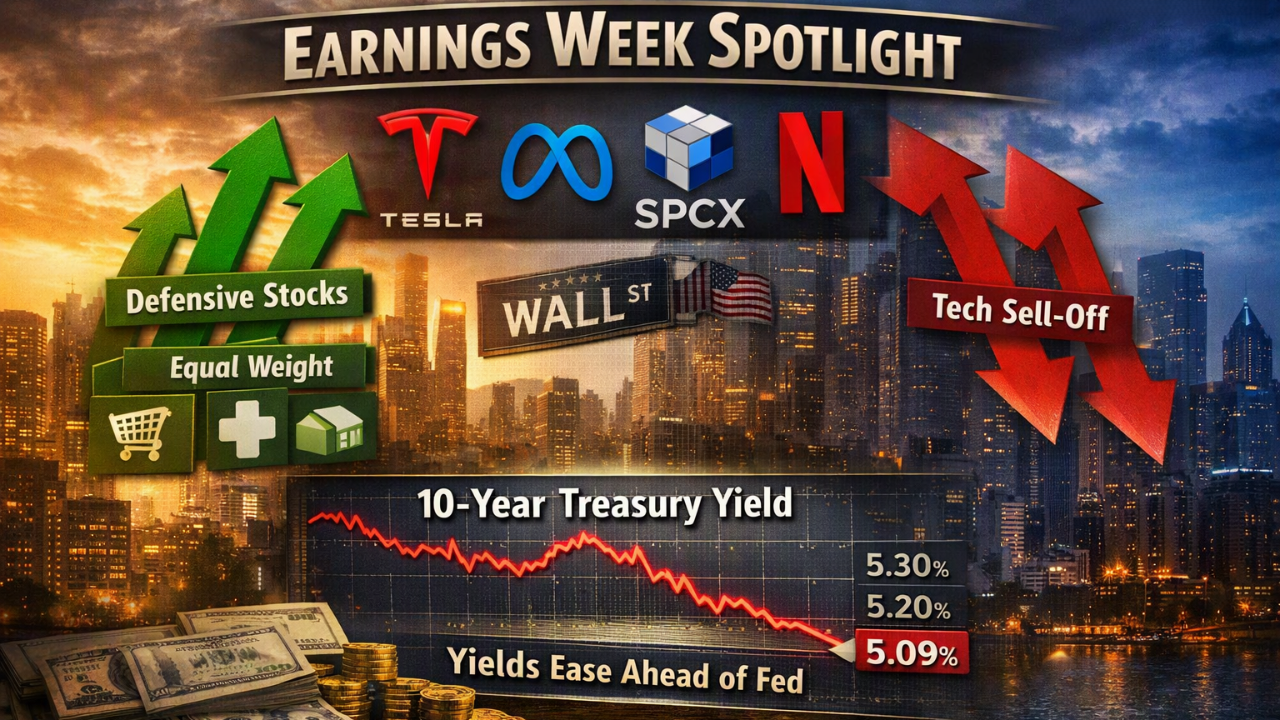
Dear Friends,
The market enters the week marked by a sharp rotation beneath the surface and an unexpected shift in bond‑market behavior just as major tech companies prepare to report earnings. Despite headline weakness in the S&P 500 and Nasdaq, breadth strengthened as most stocks advanced and defensives led, while megacap tech and AI names stumbled under rising skepticism and heavy capex pressure. The bigger surprise came from Treasurys: long‑term yields fell sharply even after two hot inflation prints, signaling that bad news may finally be priced in and that buyers are stepping in above 5%. With a “live” Fed meeting ahead, elevated rate volatility, and a crucial slate of tech earnings that will determine whether leadership can stabilize or continue to unwind, markets face a complex mix of rotation, macro uncertainty, and shifting sector dynamics that will define trading this week.
Index Performance & Market Tone
- The prior week (Oct 12) delivered a sharp divergence: S&P 500 fell nearly 2%, Nasdaq dropped over 4%, while the Dow and equal‑weight S&P (RSP) posted gains.
- Despite index weakness, 70% of S&P stocks advanced, signaling broadening breadth and a rotation away from megacap tech leadership.
- Defensive sectors (staples, healthcare, utilities) and rate‑sensitive groups (materials, industrials) outperformed as 10‑year yields retreated from multidecade highs.
Macro Drivers
- Inflation surprised hotter (CPI and PPI re‑accelerated), keeping rate pressure elevated even as yields pulled back late in the week.
- Oil touched $100 again, adding to inflation concerns and complicating the Fed’s path.
- The Fed’s Oct 27-28 meeting is now “live”: futures price a low probability of a hike, but economists see a real chance of tightening given the September inflation data.
Leadership Shift & Breadth
- Tech/AI stocks: previously the market’s “safety trade” saw their largest weekly drop since early 2025, driven by capex intensity, financing concerns, and rising skepticism about AI‑driven earnings durability.
- The SPY/RSP ratio is rolling over from a triple‑top pattern, signaling a trend reversal where equal‑weight and Dow‑style exposures outperform megacap‑heavy SPY.
- If tech continues weakening, implied correlations are likely to rise, historically a bearish feature for the S&P 500.
Earnings vs Yields: The Core Tug‑of‑War
- Earnings growth, especially in tech and energy, remains extremely strong, with the S&P 500 trading at 19x forward earnings, below 5‑ and 10‑year averages.
- But the cost of capital is rising, and the market is now forced to weigh earnings momentum against elevated yields and Fed uncertainty.
- Yields may be topping: The 10‑year failed to rise on two hot inflation prints (CPI + PPI), instead falling from 5.33% to 5.09%, a strong signal that bad news is already priced in.
Positioning Implications for This Week
- Favor rotation: defensives (staples, healthcare, utilities), industrials, materials, and equal‑weight/Dow exposures.
- Treat tech/AI as a prove‑it trade: upside requires strong earnings and capex clarity; otherwise expect continued volatility.
- Keep positioning nimble into the Fed: the October meeting is the next major volatility catalyst.
- Expect higher correlations: index volatility likely increases; relative‑value trades outperform directional bets.
Base Case for the Week
- S&P 500: mild downside bias driven by megacap drag.
- Nasdaq: high‑volatility, downside‑skewed until earnings stabilize sentiment.
- Equal‑weight & Dow: continued relative outperformance.
- Rates: volatile; any backup in yields pressures tech first.
- Macro tone: rotation, not broad risk‑off.
Want to get our Stocks to Watch Report every trading day? Get a free 7-day trial of the MyCompass Pro membership!
