
Market Briefing: Inflation, Rates, and the Next Phase of Market Leadership
Nov 09, 2026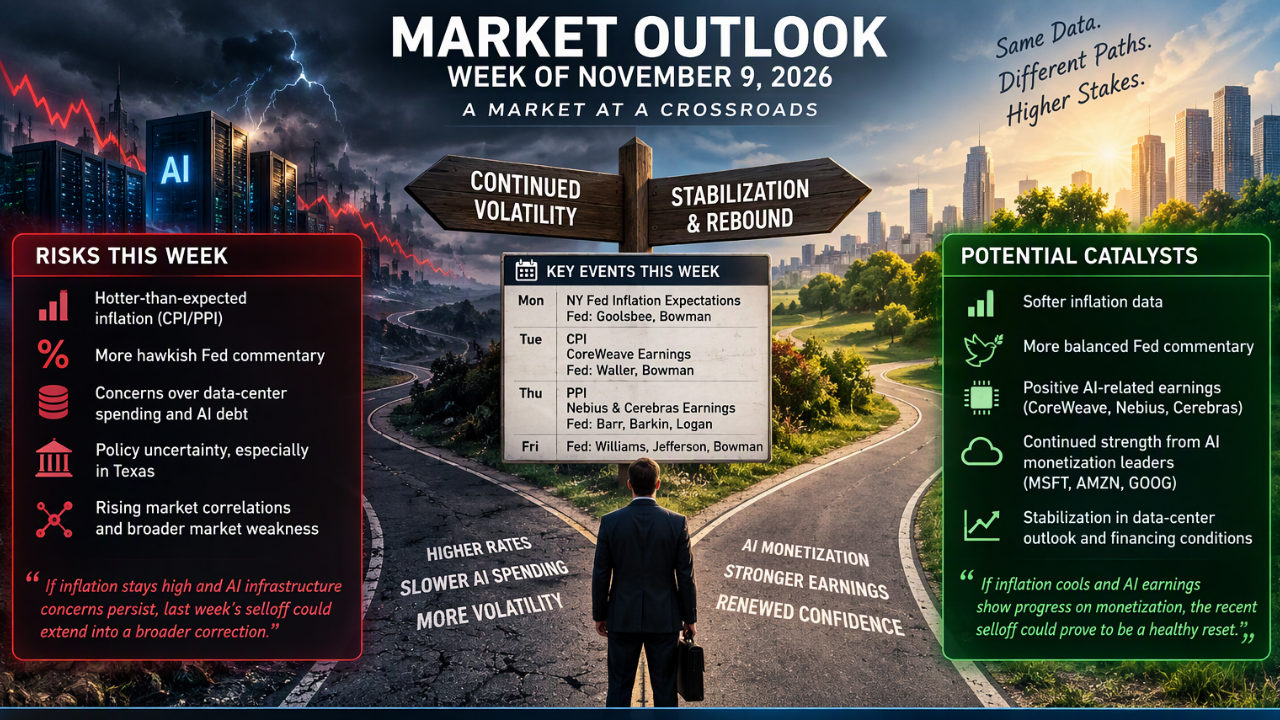
Dear Friends,
Markets enter the week at a critical inflection point after one of the sharpest risk-off moves of 2026, driven by a dramatic unwind in AI infrastructure stocks and growing concerns about the pace of future data-center spending.
Last week, the Nasdaq fell 3.4%, the S&P 500 lost 2.7%, and the Dow declined 0.9%, as investors reassessed AI-related growth expectations and digested the implications of the U.S. midterm elections.
The key debate has shifted from whether AI is real to whether AI infrastructure spending can continue at the current pace and which companies will ultimately monetize those investments.
Key Themes This Week
- Inflation Takes Center Stage
- Following October's stronger-than-expected jobs report, inflation is now the market's primary macro catalyst.
- CPI, PPI, and inflation expectations data will shape expectations for the Federal Reserve's policy path.
- Softer inflation could support a rebound in risk assets, while hotter data may reinforce higher-for-longer rate expectations and pressure growth stocks.
- AI Trade Evolves From Buildout to Monetization
- The market's focus is shifting from companies building AI infrastructure to companies generating returns from AI investments.
- Hyperscalers such as Microsoft, Amazon, and Google have remained relatively resilient as investors increasingly prioritize AI monetization over capital spending.
- Upcoming results and commentary from AI-related companies will be closely watched for signs of continued demand and spending trends.
- Data Center and Financing Concerns Remain in Focus
- Investor concerns surrounding future data-center expansion contributed significantly to last week's selloff.
- Political and regulatory uncertainty, particularly around Texas data-center development, has introduced new questions regarding the pace of future AI infrastructure growth.
- At the same time, the AI ecosystem continues to rely heavily on debt financing, making credit-market conditions increasingly important.
- Market Leadership at a Critical Juncture
- Recent weakness reflects a rotation away from AI infrastructure beneficiaries rather than a broad deterioration in economic fundamentals.
- Strong labor-market data suggests recession risks remain limited.
- The key question is whether investors ultimately view last week's selloff as a healthy reset within the AI theme or the beginning of a broader leadership unwind.
What We're Watching
- CPI and PPI inflation reports
- Fed speaker commentary throughout the week
- CoreWeave, Nebius, and Cerebras earnings and outlooks
- Treasury yields and rate expectations
- AI infrastructure spending and data-center commentary
Bottom Line
The market appears to be transitioning from an "AI buildout" narrative to an "AI profitability" narrative. While last week's selloff exposed growing concerns around infrastructure spending, financing costs, and policy uncertainty, there is little evidence that the broader AI cycle is ending. The week ahead will likely be determined by whether inflation data and AI-related earnings reinforce confidence in AI monetization and support a stabilization in market leadership. Until then, we should expect elevated volatility and continued sensitivity to both macroeconomic and AI-specific developments.
Want to get our Stocks to Watch Report every trading day? Get a free 7-day trial of the MyCompass Pro membership!
