
Market Briefing: High Yields, High Stakes: Q3 Earnings Kickoff
Oct 12, 2026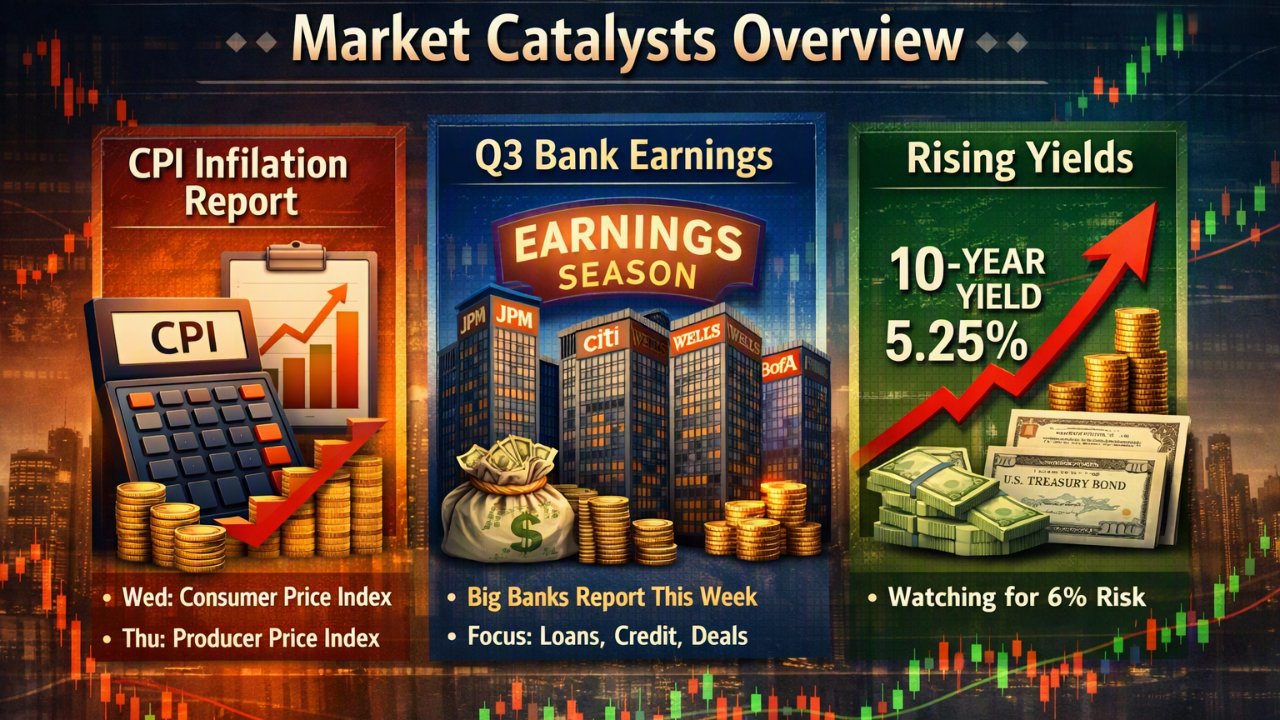
Market Briefing: High Yields, High Stakes: Q3 Earnings Kickoff
The Bull Market’s Test: CPI + Bank Earnings………
The market heads into the week of October 12 with a fragile balance of optimism and pressure, as investors brace for a pivotal stretch defined by CPI and PPI inflation data and the kickoff of Q3 earnings season led by the major banks. Stocks may be sitting near record highs, but the backdrop has grown increasingly tense: long‑term Treasury yields continue to grind above 5.25%, oil remains elevated, and concerns about tightening financial conditions are building just as companies prepare to reveal how they’ve navigated the rate shock. With AI‑driven mega‑caps still carrying the market and banks positioned to deliver the first real read on credit demand, dealmaking, and consumer health, this week’s data and earnings commentary will set the tone for whether the bull market can maintain momentum or finally feel the weight of higher‑for‑longer yields.
Macro & Rates
- Long‑term Treasury yields remain elevated (10‑year ~5.25%–5.6%), with strategists saying a move toward 6% is plausible if oil stays high, AI capex remains strong, and economic growth holds.
- Despite buyback efforts and volatility, the Treasury market remains orderly, though Friday’s dealer survey and November refunding expectations could trigger swings in long‑end yields.
- Elevated yields continue to pressure equity valuations, especially for high‑duration tech and AI names.
Equities & AI
- The S&P 500 and Nasdaq hit fresh record highs even as yields climbed, showing the market’s reliance on AI‑driven earnings strength.
- The four‑year bull market remains intact, historically entering a strong fifth year, but rising yields increase competition from bonds offering ~5%+ returns with lower volatility.
Q3 Earnings Season (Banks Kick Off Tuesday)
- Major banks (JPM, Citi, Wells, Goldman, BofA, MS) begin reporting Q3 earnings, with YoY EPS growth expected across the largest six banks.
- Sequential EPS will decline from Q2 due to the one‑time SpaceX IPO spike.
- Investors are focused on credit demand, dealmaking trends, loan appetite, and commentary on how high rates and oil are affecting corporate and consumer borrowing.
- Bank stocks have fallen ~12% since mid‑August as markets price in slower deal activity and weaker sentiment.
Earnings Expectations for the Broader Market
- Analysts expect ~29.6% S&P 500 earnings growth for Q3, the third straight quarter above 25%.
- Strong earnings expectations have been essential in offsetting the drag from high rates and elevated oil.
- Tech and AI‑exposed companies remain the primary earnings engine, while non‑AI sectors may show more conservative guidance.
Market Breadth & Positioning
- Breadth has narrowed, with industrials, transports, and discretionary weakening while staples outperform, signaling cautious positioning beneath index‑level strength.
- Analysts note breadth often catches up as FOMO pushes sidelined investors into laggards.
Want to get our Stocks to Watch Report every trading day? Get a free 7-day trial of the MyCompass Pro membership!
